Anthem is one of the largest sellers of small business health insurance in the country, and its parent Elevance Health serves about 100 million people with nearly 100,000 employees. The blue-card network it licenses is the biggest in America, and Anthem advertises access to a network covering 95% of doctors and 96% of hospitals. What a founder actually buys, though, is a contract in one state, underwritten by one filing, priced on one risk pool. The brand that reaches 106 million people has about as much to do with your January renewal as the logo on the card.
The short version
- What it is
- A BCBS licensee selling small group cover in 13 states
- Their market
- Small groups of 2 to 100 employees
- Their network claim
- 95% of US doctors and 96% of hospitals, association-wide
- Prescience Diamond
- Health plan only, you keep your payroll
Anthem sells one product in 13 states, and the page reads like 50
The small business page sets out the offer plainly: cover for groups with "2 to 100 employees," a portfolio that includes high-deductible options and "a wide choice of networks," and a buying process that Anthem says has no special enrollment window, so a small business can buy at any time of year. That last point is genuinely useful and rarer than it should be.
The state list is where the branding gets ahead of the reality. Anthem writes small group business in Colorado, Connecticut, Georgia, Indiana, Kentucky, Maine, Missouri outside the Kansas City counties, Nevada, New Hampshire, New York in 17 southeastern counties, Ohio, Virginia outside the northern suburbs, and Wisconsin. If you hire in California, Texas, Florida or Illinois, the blue card your employee recognises may not be sold by Anthem at all, because the licence belongs to a different company in that state.
The association is real and it is not a single insurer. The blue-card system is a set of independent licensees that share branding and a reciprocal network agreement. Anthem is one licensee, operating as Elevance Health, and the site cites the association figure directly: "One in three Americans carries a BCBS card — over 106 million members." That is a statement about the system, not about the policy your 40-person company is being quoted.
95% of doctors is a system number, and the contract is narrower
Anthem's network claim is the strongest thing on the page: "a network that includes 95% of doctors and 96% of hospitals in the U.S.," with employers able to find providers "within 10 miles of their home." For a founder whose team is spread across a metro, that is close to the whole argument. Nobody wants to tell a new hire their oncologist is out of network.
Two things are true at once here. The reciprocal agreement means a member travelling or living in another licence area can usually use a local blue-card network, which is a real and unusual benefit for a distributed team. And the 95% figure is measured across the association's commercial, Medicare and Medicaid books, so it is a portfolio average rather than a promise about your plan tier in your county.
The practical test is unchanged from every other large carrier. Take the five providers your team actually uses, plus the nearest hospital and the nearest children's hospital, and check each against the plan identifier on the quote, not the brand. Anthem publishes a provider lookup that lets you do it. The step takes twenty minutes and it is the difference between a network claim and a network.
| Question | Why it decides the plan |
|---|---|
| Which Anthem entity and state filing is this | The brand is licensed per state, not nationally |
| Which network name is on this plan code | Anthem sells several tiers at different prices |
| Are our team's specialists in that tier | Continuity matters more than a small premium gap |
| Does the reciprocal blue-card access apply to this product | Not every product carries the same travel cover |
| What is the out-of-network rate | The broadest network still has one |
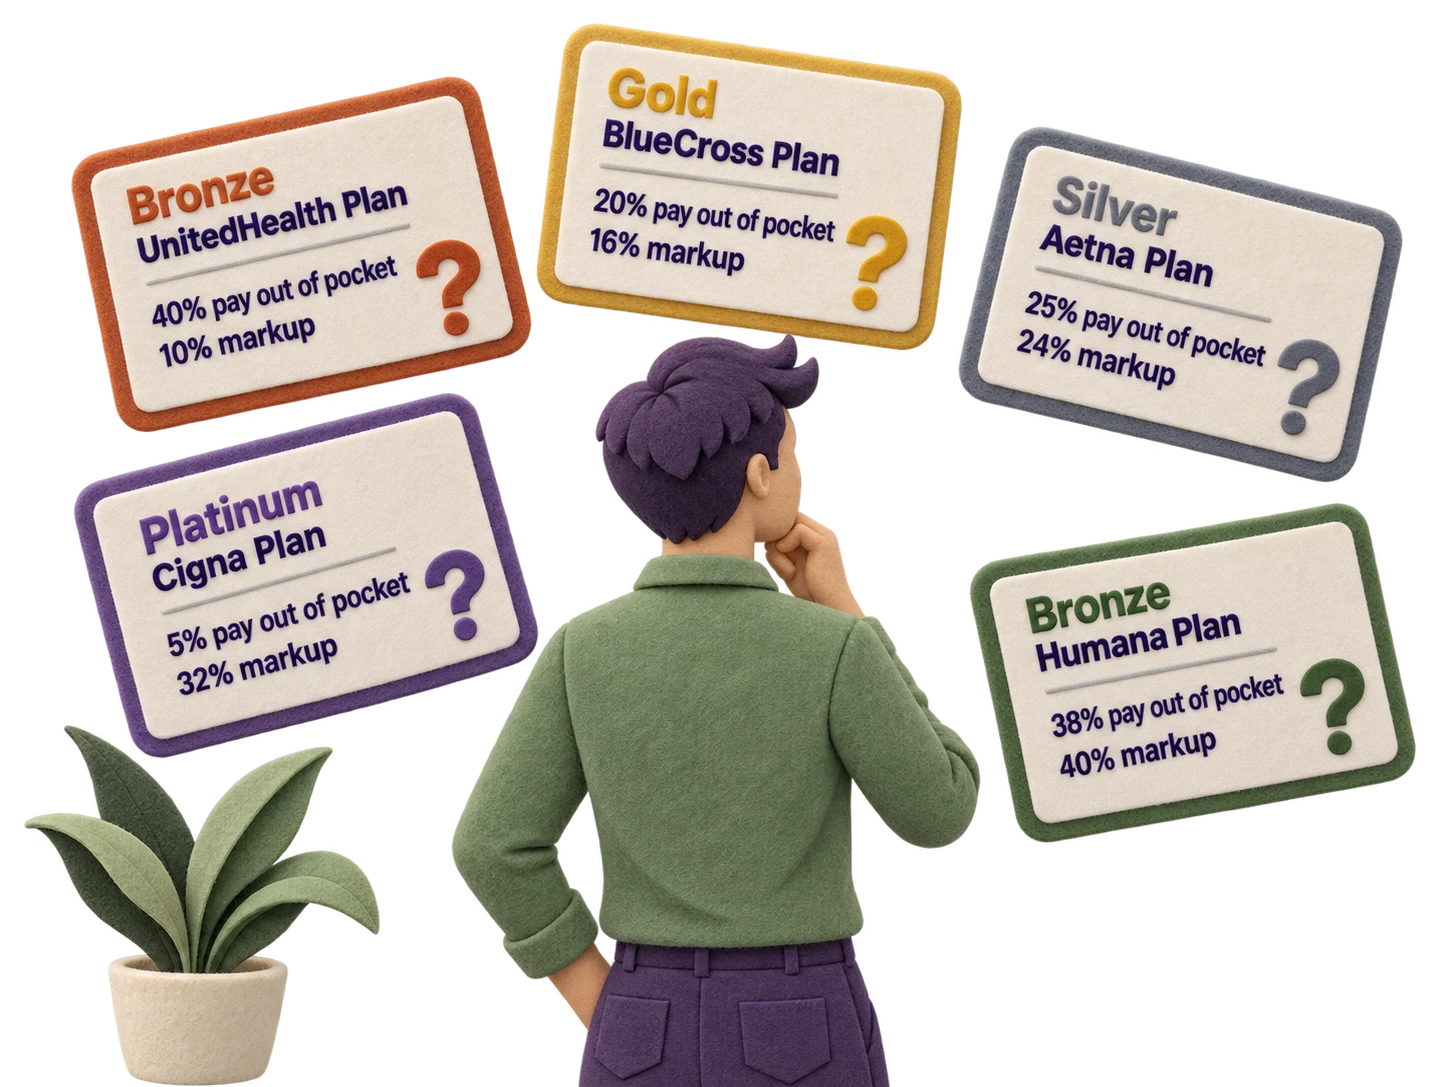
A fully insured renewal is priced on your pool, whatever the logo
Anthem's small group products are fully insured, which means the carrier collects a premium and carries the claims risk. That is the simplest arrangement to administer and it is the one most small employers start with. It also means the premium is set on the carrier's filed rates for age, location, family size and tobacco, and it is repriced every renewal. In the ACA small group market your own claims cannot be a rating factor. A bad claims year does not come back to you as a surcharge on paper. What you feel is the movement in the filed rates themselves, and that number is published once a year by people who never saw your census.
Nothing about a 106-million-member association changes that arithmetic. The carrier's scale gives it leverage over hospital contracts, which is worth something real. It does not give your group a share of that leverage, because your group is one rating unit inside a pool of other rating units, and the pool's trend is what moves your renewal.
Elevance, the parent, describes itself as "transforming from a traditional health benefits organization into a lifetime trusted health partner," serving about 100 million people at every stage of health. That is an accurate description of a business that wants to sell you more than medical cover, and it explains the range of products attached to the small group page.
One employee with a $400,000 claim does not raise your small group premium directly. This is where the market is often misdescribed, and it matters because it changes the shopping advice. Under the ACA rating rules a small group premium may vary only by age, tobacco use, location and family enrollment. Your group's health status and its claims record are not permitted factors. One serious diagnosis on the team will not be billed back to you next January, and a year of low claims buys you no discount either. The premium you renew into is the carrier's filed rate for the same people.
Large group and level-funded products are different. Above the small group threshold, and on a level-funded plan at any size, the carrier does use your group's own experience, and a single large claim can move the whole group's rate. That is why the small group answer, which is that your claims stay in the pool, is not the answer for a 200-person company shopping the same brand.
The add-ons are the interesting part, and they are sold separately
Anthem bundles a more complete benefits suite than most small group carriers: dental with 100% in-network preventive, vision through a network the site says covers more than 40,000 eye doctors at more than 30,000 locations, life and disability arranged through The Standard, and an employee assistance programme it says comes at no added cost. Pharmacy runs through CarelonRx, a pharmacy benefit manager Anthem owns, which the company presents as a custom-built advantage.
Each of these is a separate line on the invoice and, more importantly, a separate opportunity for a fee to be taken somewhere in the chain. An owned pharmacy benefit manager is a real integration and it is also a party that earns a margin on your drug spend, and that margin is not visible on the premium line. That is normal in this market and it is worth naming.
The clinical pieces are the familiar large-carrier menu: 24/7 online visits with board-certified doctors, the Sydney Health app, preventive care at 100% in network under the ACA rules, and a whole-person programme the company calls Whole Health Connection. These are legitimate benefits. They are also the parts of the package that employees use least, while the deductible and the network are the parts they meet first.
- Medical: fully insured small group, 2 to 100 employees, several network tiers at different prices.
- Pharmacy: CarelonRx, an Anthem-owned benefit manager. Ask what the margin is.
- Dental and vision: sold alongside, with their own networks and limits.
- Life and disability: arranged through a third party, The Standard.
- Employee assistance: described as no added cost, which usually means a bundled number of sessions.
Who Anthem fits, and who should look elsewhere
The case for Anthem is narrow and real. If your employees value the blue card, if your team travels or lives across state lines and wants reciprocal access, and if you are in one of the 13 states where Anthem writes the business, you get the widest provider reach in the market plus a carrier that answers on a local basis. That is a strong answer and many companies should take it.
The case against is not about the network. It is that a fully insured plan is repriced annually on a pool, the network tiers are priced differently for a reason, and the state-by-state licensing means a company hiring nationally ends up running several contracts with several entities, each with its own renewal and its own rules.
| Your company | Does Anthem make sense? |
|---|---|
| A team in one of Anthem's 13 states, hiring locally | Strong fit. The network is the product |
| A distributed team that wants reciprocal access | Good fit, if the specific product carries it. Confirm in writing |
| A company hiring in California, Texas or Florida | Only through another licensee. Check who holds the contract |
| An employer worried one big claim will follow it | Small group covers that. Claims are not a rating factor, so it will not follow you |
| A founder who wants one fixed price for the year | You get a fixed premium, then a repricing at renewal |
| A team of 25 with healthy, predictable claims | Worth comparing against a plan whose price is fixed in a quote |
Anthem is a serious carrier with the best network story in the market, and none of the criticism above is about quality of care. It is about structure: the association's scale is not shared with your risk pool, the licence is granted state by state, and the price is set again every year on a record you cannot change by choosing a different logo.